

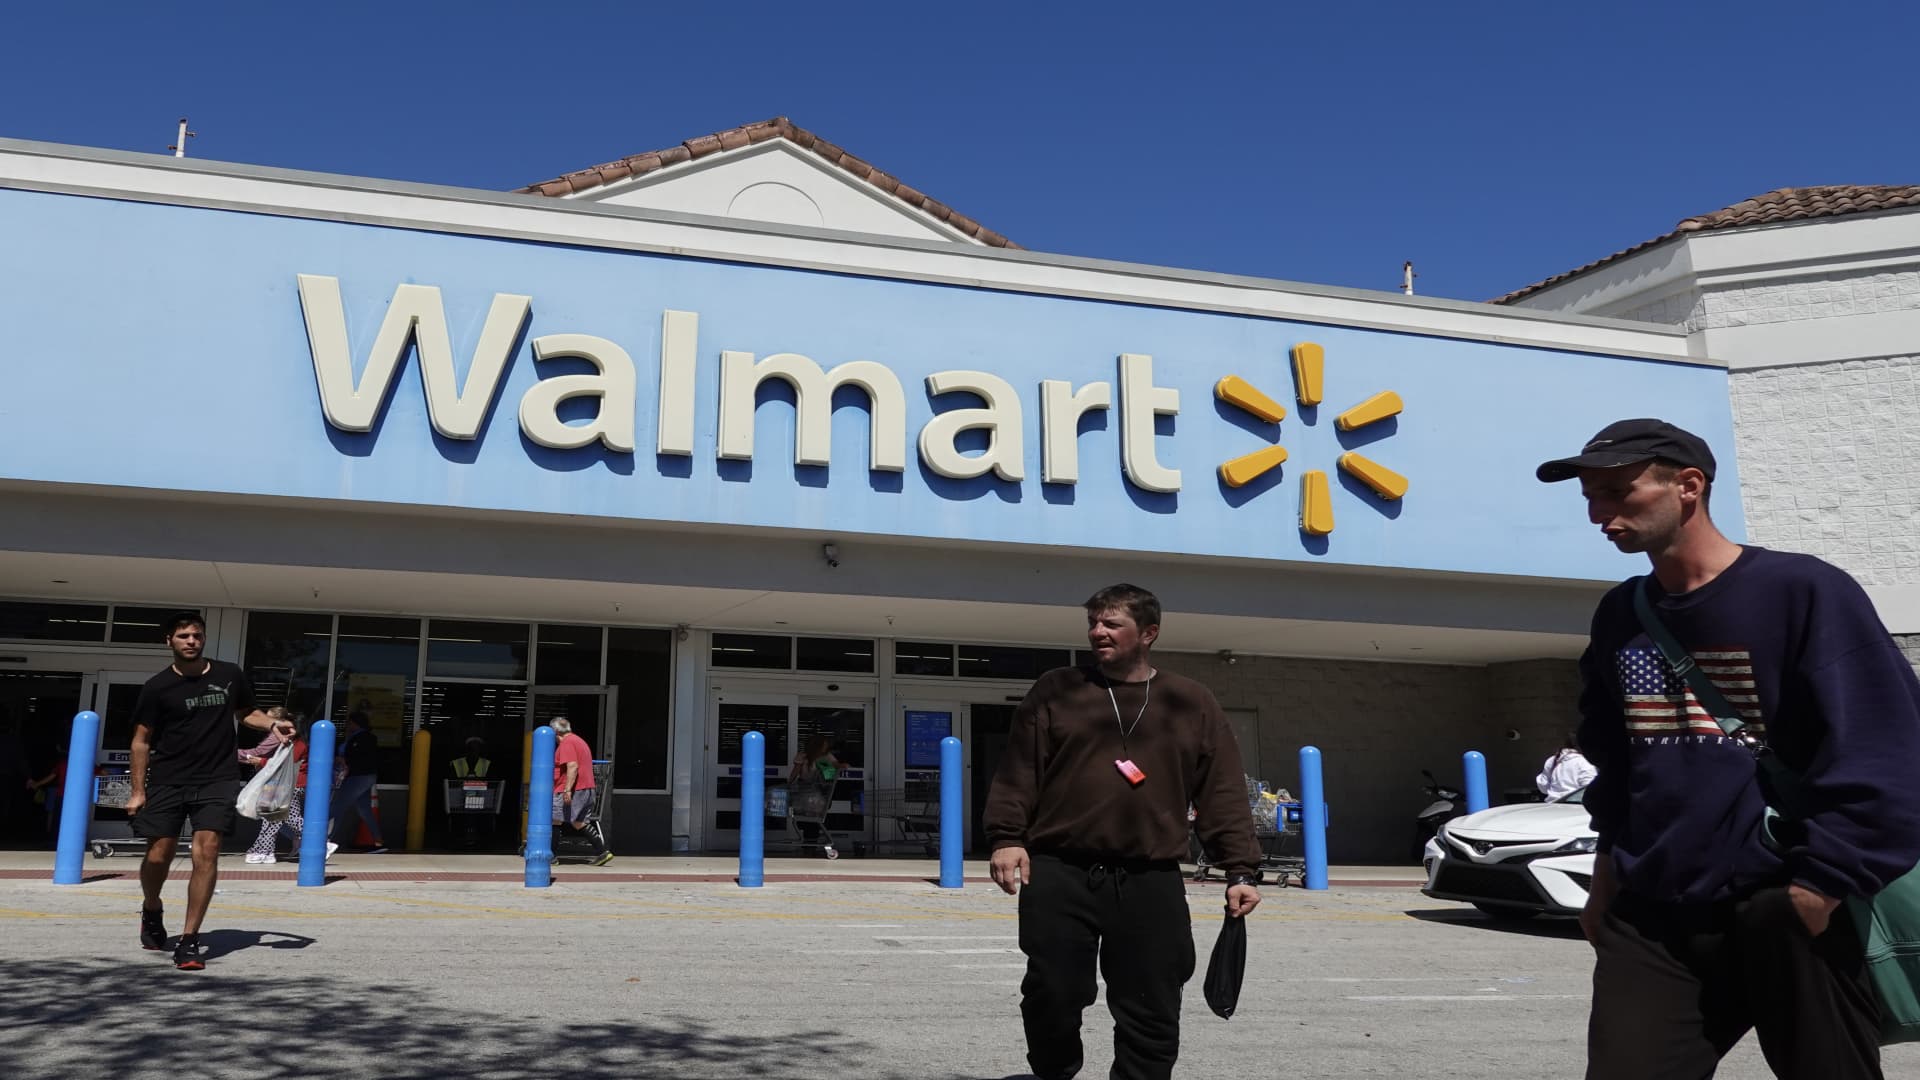
Customers shop in a Walmart Supercenter on February 20, 2024 in Hallandale Beach, Florida.
Joe Raedle | Getty Images News | Getty Images
Walmart’s majority-owned fintech startup One has begun offering buy now, pay later loans for big-ticket items at some of the retailer’s more than 4,600 U.S. stores, CNBC has learned.
The move puts One in direct competition with Affirm, the BNPL leader and exclusive provider of installment loans for Walmart customers since 2019. It’s a relationship that the Bentonville, Arkansas, retailer expanded recently, introducing Affirm as a payment option at Walmart self-checkout kiosks.
It also likely signals that a battle is brewing in the store aisles and ecommerce portals of America’s largest retailer. At stake is the role of a wide spectrum of players, from fintech firms to card companies and established banks.
One’s push into lending is the clearest sign yet of its ambition to become a financial superapp, a mobile one-stop shop for saving, spending and borrowing money.
Since it burst onto the scene in 2021, luring Goldman Sachs veteran Omer Ismail as CEO, the fintech startup has intrigued and threatened a financial landscape dominated by banks â and poached talent from more established lenders and payments firms.
But the company, based out of a cramped Manhattan WeWork space, has operated mostly in stealth mode while developing its early products, including a debit account released in 2022.
Now, One is going head-to-head with some of Walmart’s existing partners like Affirm who helped the retail giant generate $648 billion in revenue last year.
Walmart’s Fintech startup One is now offering BNPL loans in Secaucus, New Jersey.
Hugh Son | CNBC
On a recent visit by CNBC to a New Jersey Walmart location, ads for both One and Affirm vied for attention among the Apple products and Android smartphones in the store’s electronics section.
Offerings from both One and Affirm were available at checkout, and loans from either provider were available for purchases starting at around $100 and costing as much as several thousand dollars at an annual interest rate of between 10% to 36%, according to their respective websites.
Electronics, jewelry, power tools and automotive accessories are eligible for the loans, while groceries, alcohol and weapons are not.
Buy now, pay later has gained popularity with consumers for everyday items as well as larger purchases. From January through March of this year, BNPL drove $19.2 billion in online spending, according to Adobe Analytics. That’s a 12% year-over-year increase.
Walmart and One declined to comment for this article.
Who stays, who goes?
One’s expanding role at Walmart raises the possibility that the company could force Affirm, Capital One and other third parties out of some of the most coveted partnerships in American retail, according to industry experts.
“I have to imagine the goal is to have all this stuff, whether it’s a credit card, buy now, pay later loans or remittances, to have it all unified in an app under a single brand, delivered online and through Walmart’s physical footprint,” said Jason Mikula, a consultant formerly employed at Goldman’s consumer division.
Affirm declined to comment about its Walmart partnership. Shares of Affirm climbed 3% Tuesday, rebounding after falling more than 8% in premarket activity.
For Walmart, One is part of its broader effort to develop new revenue sources beyond its retail stores in areas including finance and health care, following rival Amazon’s playbook with cloud computing and streaming, among other segments. Walmart’s newer businesses have higher margins than retail and are a part of its plan to grow profits faster than sales.
In February, Walmart said it was buying TV maker Vizio for $2.3 billion to boost its advertising business, another growth area for the retailer.
‘Bank of Walmart’
When it comes to finance, One is just Walmart’s latest attempt to break into the banking business. Starting in the 1990s, Walmart made repeated efforts to enter the industry through direct ownership of a banking arm, each time getting blocked by lawmakers and industry groups concerned that a “Bank of Walmart” would crush small lenders and squeeze big ones.
To sidestep those concerns, Walmart adopted a more arms-length approach this time around. For One, the retailer created a joint venture with investment firm firm Ribbit Capital â known for backing fintech firms including Robinhood, Credit Karma and Affirm â and staffed the business with executives from across finance.
Walmart has not disclosed the size of its investment in One.
The startup has said that it makes decisions independent of Walmart, though its board includes Walmart U.S. CEO, John Furner, and its finance chief, John David Rainey.
One doesn’t have a banking license, but partners with Coastal Community Bank for the debit card and installment loans.
After its failed early attempts in banking, Walmart pursued a partnership strategy, teaming up with a constellation of providers, including Capital One, Synchrony, MoneyGram, Green Dot, and more recently, Affirm. Leaning on partners, the retailer opened thousands of physical MoneyCenter locations within its stores to offer check cashing, sending and receiving payments, and tax services.
From paper to pixels
But Walmart and One executives have made no secret of their ambition to become a major player in financial services by leapfrogging existing players with a clean-slate effort.
One’s no-fee approach is especially relevant to low- and middle-income Americans who are “underserved financially,” Rainey, a former PayPal executive, noted during a December conference.
“We see a lot of that customer demographic, so I think it gives us the ability to participate in this space in maybe a way that others don’t,” Rainey said. “We can digitize a lot of the services that we do physically today. One is the platform for that.”
One could generate roughly $1.6 billion in annual revenue from debit cards and lending in the near term, and more than $4 billion if it expands into investing and other areas, according to Morgan Stanley.
Walmart can use its scale to grow One in other ways. It is the largest private employer in the U.S. with about 1.6 million employees, and it already offers its workers early access to wages if they sign up for a corporate version of One.
Walmart’s next card
There are signs that One is making a deeper push into lending beyond installment loans.
Walmart recently prevailed in a legal dispute with Capital One, allowing the retailer to end its credit-card partnership years ahead of schedule. Walmart sued Capital One last year, alleging that its exclusive partnership with the card issuer was void after it failed to live up to contractual obligations around customer service, assertions that Capital One denied.
The lawsuit led to speculation that Walmart intends to have One take over management of the retailer’s co-branded and store cards. In fact, in legal filings Capital One itself alleged that Walmart’s rationale was less about servicing complaints and more about moving transactions to a company it owns.
“Upon information and belief, Walmart intends to offer its branded credit cards through One in the future,” Capital One said last year in response to Walmart’s suit. “With One, Walmart is positioning itself to compete directly with Capital One to provide credit and payment products to Walmart customers.”
A Capital One Walmart credit card sign is seen at a store in Mountain View, California, United States on Tuesday, November 19, 2019.
Yichuan Cao | Nurphoto | Getty Images
Capital One said last month that it could appeal the decision. The company declined to comment further.
Meanwhile, Walmart said last year when its lawsuit became public that it would soon announce a new credit card option with “meaningful benefits and rewards.”
One has obtained lending licenses that allow it to operate in nearly every U.S. state, according to filings and its website. The company’s app tells users that credit building and credit score monitoring services are coming soon.
Catching Cash App, Chime
And while One’s expansion threatens to supersede Walmart’s existing financial partners, Walmart’s efforts could also be seen as defensive.
Fintech players including Block’s Cash App, PayPal and Chime dominate account growth among people who switch bank accounts and have made inroads with Walmart’s core demographic. The three services made up 60% of digital player signups last year, according to data and consultancy firm Curinos.
But One has the advantage of being majority owned by a company whose customers make more than 200 million visits a week.
It can offer them enticements including 3% cashback on Walmart purchases and a savings account that pays 5% interest annually, far higher than most banks, according to customer emails from One.
Those terms keep customers spending and saving within the Walmart ecosystem and helps the retailer better understand them, Morgan Stanley analysts said in a 2022 research note.
“One has access to Walmart’s sizable and sticky customer base, the largest in retail,” the analysts wrote. “This captive and underserved customer base gives One a leg up vs. other fintechs.”
Read the original article here